HF Sinclair to Separate Lubricants Arm and Close Canada’s Largest Base Oil Plant
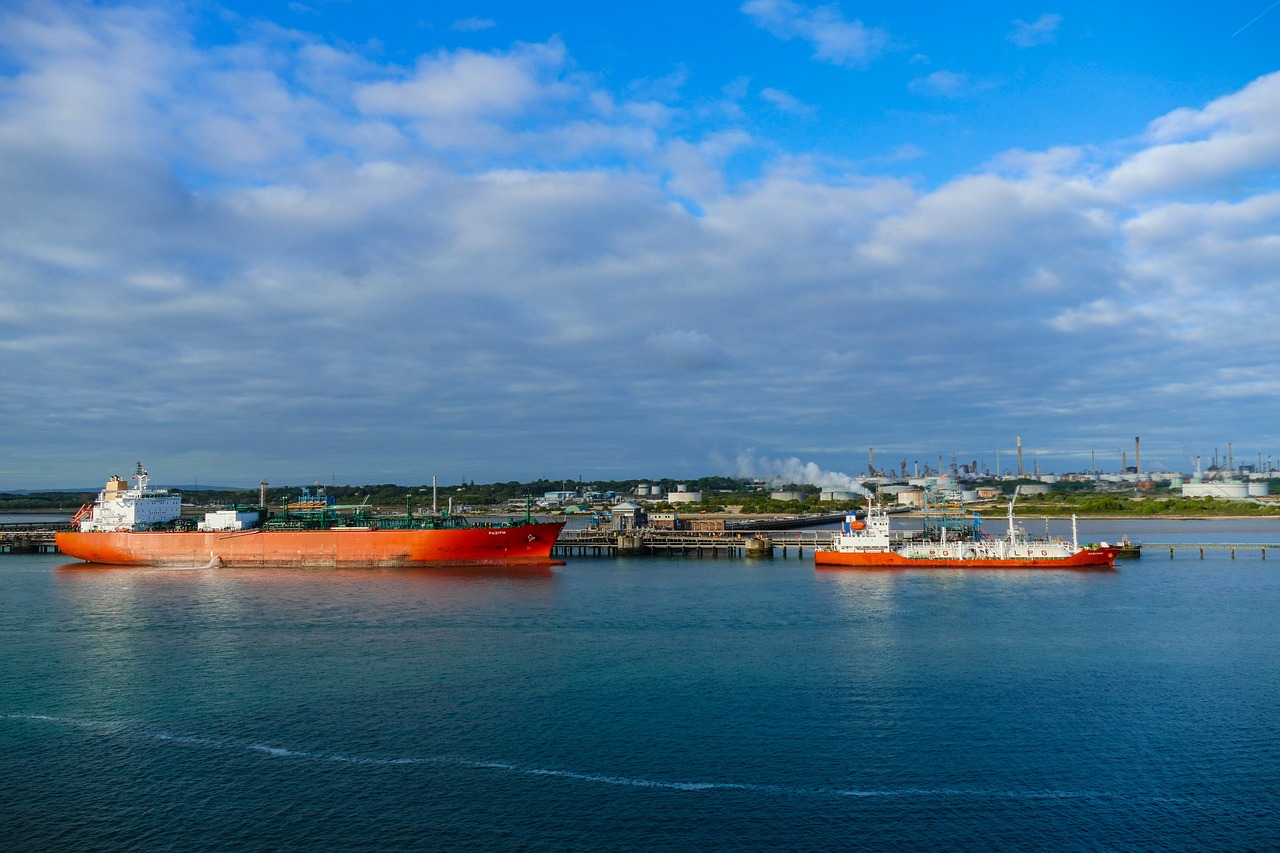
HF Sinclair has announced that it intends to separate its lubricants and specialties business into an independent listed company, and to close its base oil refinery in Mississauga, Ontario. Transition work is expected to be substantially complete during 2027. The announcement was made on 28 July, and the following day the Unifor union issued a public statement condemning the decision to shut Canada's largest base oil plant.
What Was Announced
Under the plan, the spun-off entity would operate on an asset-light model, leaning on technical capability, global brand recognition and existing sales channels in pursuit of greater financial flexibility and steadier free cash flow. The company has described the separation as a way to unlock value by creating two more focused businesses.
Mississauga is the largest base oil production site in Canada. Research laboratories, lubricant blending and packaging operations, and supply chain and logistics functions are expected to remain in the region even as the refinery itself closes. The separation is expected to take 12 to 18 months and does not require a shareholder vote.
The business being separated carries several established brands, including Petro-Canada Lubricants, which HF Sinclair acquired from Suncor in 2017, as well as Red Giant Oil, Sonneborn and HollyFrontier Specialty Products. In the second quarter of 2026, the segment reported adjusted EBITDA of US$207 million.
Supply Contracted Before Divestment
Read from the supply side, the sequence matters more than the headline. HF Sinclair has already put commercial agreements in place with two global base oil producers.
A long-term Group III supply agreement with SK Enmove runs alongside SK Enmove becoming the exclusive distributor of YUBASE Group III base oil in key North American regions. Separately, an agreement with Chevron Products Company gives HF Sinclair exclusive distribution rights for Chevron Group II base oil across Canada and in the US areas it currently serves, effective 1 May 2027.
The company's Tulsa, Oklahoma refinery is to continue supplying Group I and specialty products. Taken together, these arrangements mean the separated business would still offer a full Group I, Group II and Group III range even without its own Canadian base oil plant. Securing raw material supply first and divesting the heavy asset second is the order that keeps a spin-off from becoming a supply risk to itself.
What It Means for Buyers
For anyone buying in North America, the announcement changes the shape of Group II and Group III availability more than it changes any single contract. When a plant of this size exits, the volumes it supplied are not lost — they are reallocated across remaining producers, imports and distributors.
Reallocation takes time, and that window is when grades go short in individual markets. A buyer's own contract may be untouched on paper while the grade it depends on becomes harder to obtain, because several other buyers are being redirected at the same time.
There is a second, quieter exposure. Where a contract names a brand but not a supplier, a specification and a delivery window, a change in the supplying plant or in the serving channel can be absorbed by that contract without triggering any commercial discussion. Contracts that name all three are more durable through a transition than contracts that name only a brand.
The Wider Allocation Question
The closure is not happening in isolation. Middle East capacity has been kept offline by conflict, and South Korea's position as a major Group III producing region has strengthened as a result — a shift that the HF Sinclair agreement with SK Enmove reflects directly. Chevron's separate reorganisation of its North American distribution network points the same way: assets and channels are being exchanged, and the competitive map is being redrawn around availability and logistics rather than around who owns the plant.
For an additive or finished-lubricant producer, the practical implication is that the supply map used for last year's sourcing plan is no longer the supply map that applies. Reallocation is a process measured in years, and its effects arrive in individual markets at different times.
What to Do Before 2027
For blenders with North American exposure, this is a reasonable moment to re-confirm qualified second sources and to check that approvals, not just prices, are in place ahead of the transition. A second source that has been technically approved and holds a live specification is a real option; a second source that exists only as a name on a list is not.
It is also worth mapping which of a company's own grades depend on Group II and Group III volumes from North America, and how much cover each of those grades carries. The transition is expected to run through 2027, which leaves planning time — but planning time is only useful when it is used before the allocation window opens rather than during it.
Bottom line
A 12-to-18-month separation, a Canadian plant closure and two pre-signed supply agreements add up to a reallocation of North American Group II and Group III volumes rather than an immediate shortage. The buyers who manage it well will be the ones whose second sources were approved, specified and documented well before the transition began.
Related news
Group III Base Oil: What a 235% Reference-Price Move Tells Blenders
Delegates at the Asian Lubricant Exhibition in early September were shown a set of trading indications that few buyers had planned for at the start of the year.…
Read more
China Base Oil Spot Gains 7.6% in a Week as September Costs Bite
Chinese base oil spot prices accelerated into September, and the pace of the move has reset cost assumptions across the downstream chain. Monitoring data for 2 September put…
Read more
Jinan Refinery Ships First High-Viscosity Group II Cargo to Southeast Asia
Sinopec's Jinan refinery has loaded and dispatched its first batch of high-viscosity Group II 10 base oil to Southeast Asia, opening a toll-processing export channel for the site.…
Read more